Now Reading: Hatsun Agro Q2 profit up 6% on revenue of Rs 2,898 crore
-
01
Hatsun Agro Q2 profit up 6% on revenue of Rs 2,898 crore

The Story in Brief
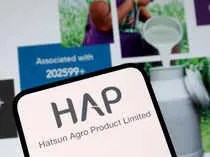
Hatsun Agro Product Ltd reported a 5.6 to 6% rise in net profit to about Rs 116 crore for the September quarter of FY2026-27, compared with Rs 110 crore a year earlier, driven by sustained consumer demand. Revenue from operations grew 19% to Rs 2,898 to 2,902 crore, as expenses climbed to Rs 2,750 crore from Rs 2,284 crore.
Chairman R G Chandramogan cited geopolitical uncertainties, El Nino-related factors and inflation in agricultural input costs as industry challenges. The company sold 288 crore consumer packs over six months, averaging 1.58 crore packs a day, and said it will focus on direct consumer sales and expansion in Maharashtra and Odisha.
EBITDA margin fell to 11.4% from 13.4% a year earlier, CNBC-TV18 reported, while Hatsun said its margins were stronger than the industry. The company’s stock closed 5.55% lower at Rs 1,072.90 on the NSE on 22 October.
Indian Opinion Analysis
The three outlets report identical financial figures and attribute the same chairman quote, making this uniform coverage of a routine earnings release. Economic Times leads with the profit rise and total income, framing the result as strong sales despite industry hurdles. CNBC-TV18 foregrounds the margin squeeze, noting EBITDA margin fell 200 basis points, and adds the stock price drop. Business Line leads with the profit increase and revenue growth but omits the margin contraction. Together the coverage shows a company growing top line while facing cost pressure, the stock decline provides a market check on the earnings optimism. Hatsun's next focus is on direct-to-consumer expansion in Maharashtra and Odisha.
Coverage: 3 sources, 3 neutral
Sources (3): economictimes.indiatimes.com (neutral report), cnbctv18.com (neutral report), thehindubusinessline.com (neutral report)
This brief was synthesised by AI from the 3 sources linked above, so one read covers every framing they carry. Methodology and corrections.