
Now Reading: Goldman Sachs downgrades Ola Electric to Sell, target at Rs 23
-
01
Goldman Sachs downgrades Ola Electric to Sell, target at Rs 23

The Story in Brief
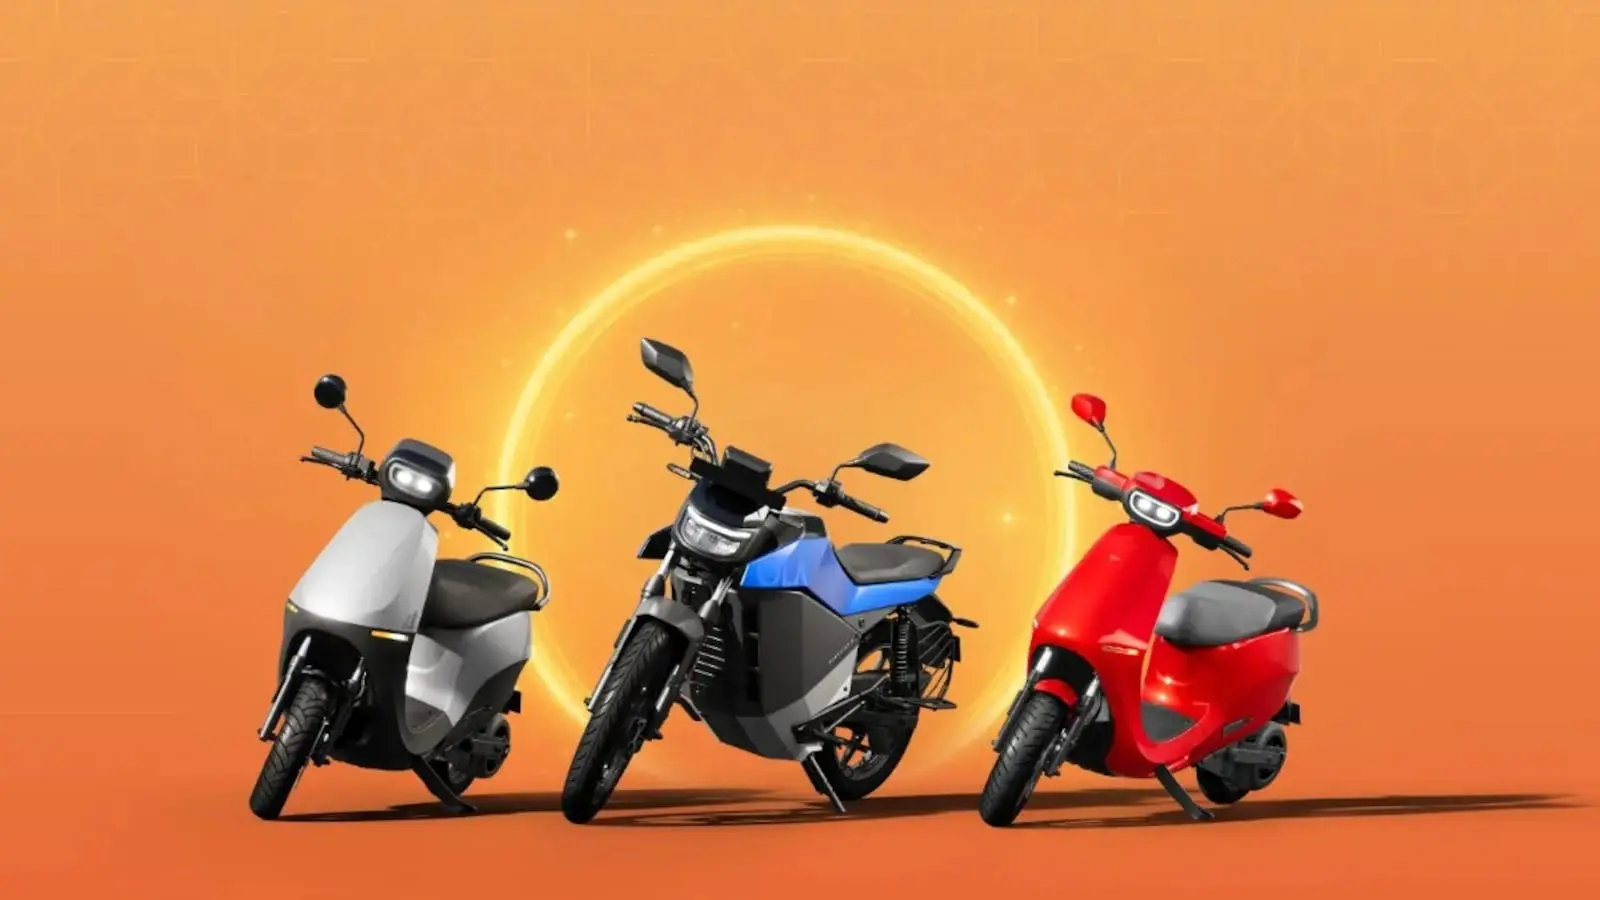
Goldman Sachs has downgraded Ola Electric Mobility to ‘Sell’ from ‘Neutral’ and cut its target price to Rs 23 from Rs 39.28, implying a 28% downside from current levels. The brokerage cited concerns over the company’s ability to generate sustainable free cash flow, elevated interest costs, and high capital expenditure requirements for its battery cell and electric two-wheeler businesses. Revenue estimates for FY27 to FY29 have been cut by up to 10%.
Shares fell as much as 5% to Rs 30.48 on the BSE on Friday, 23 October. The downgrade adds to a cautious outlook: none of the eight analysts covering Ola Electric have a ‘Buy’ rating, with seven ‘Sell’ and one ‘Hold’. The company’s rights issue, priced at Rs 27 per share, opened on Thursday, 22 October, and will close on 30 October. In September, Ola Electric sold 12,894 electric two-wheelers, giving it a 6.5% market share, down from 7.6% in August.
Indian Opinion Analysis
All three outlets report the same core facts: Goldman Sachs’ downgrade, the Rs 23 target, and the revenue estimate cut. NDTV Profit leads with the free cash flow concern, while CNBC-TV18 adds detail on the required revenue multiple (3.6 to 7.1 times FY26 revenue) and notes the departure of the battery-cell business head. Economic Times furthermore includes the rights issue terms, Q1 results, and market share data from Vahan. The coverage is uniform business reporting with no discernible editorial slant, the differences are only in breadth of supplementary data. Investors will watch Ola Electric’s ability to achieve positive consolidated EBITDA and the outcome of its rights issue, which closes on 30 October.
Coverage: 3 sources, 3 neutral
Sources (3): ndtvprofit.com (neutral report), economictimes.indiatimes.com (neutral report), cnbctv18.com (neutral report)
This brief was synthesised by AI from the 3 sources linked above, so one read covers every framing they carry. Methodology and corrections.