Now Reading: HAL Q1 revenue rises 14% to Rs 5,515 crore, stock up 45%
-
01
HAL Q1 revenue rises 14% to Rs 5,515 crore, stock up 45%



State-owned Hindustan Aeronautics (HAL) reported a consolidated net profit of Rs 1,589.68 crore for the June quarter, up 14.9% year on year, as revenue rose 14.4% to Rs 5,515.17 crore, beating its…
The Story in Brief
State-owned Hindustan Aeronautics (HAL) reported a consolidated net profit of Rs 1,589.68 crore for the June quarter, up 14.9% year on year, as revenue rose 14.4% to Rs 5,515.17 crore, beating its own 10, 12% growth guidance. EBITDA margin improved to 27.9% from 26.8%, despite a 24.5% jump in raw material costs that compressed gross margin by 280 basis points.
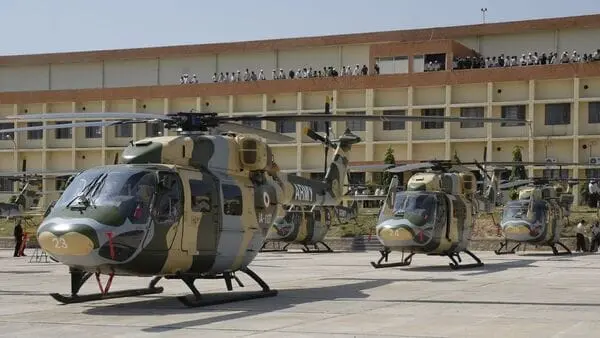
The company’s order book stood at Rs 2.54 lakh crore at the end of FY26, 7.5 times trailing sales. Revenue growth this year hinges on deliveries of the Tejas Mk1A light combat aircraft and HTT-40 trainer, expected in the latter half of FY27 after engine supply delays from GE eased. Brokerages are split: Motilal Oswal and Anand Rathi rate the stock a ‘Buy’ with a target of Rs 5,800, while JM Financial has ‘Add’ at Rs 4,770 and InCred Equities ‘Hold’. Since April, HAL shares have rallied 45% to around Rs 4,990.
The Indian Opinion
The Tejas delivery narrative dominates the bull case, but gross margin contracted 280 basis points and EBITDA margin remains below the 30, 31% target. The Rs 15,000-crore capex plan may squeeze cash flows before deliveries ramp up. With the stock at 29x forward earnings, above its long-term average, investors are pricing in near-perfect execution. Ask: how many Tejas aircraft will actually be delivered in H2 FY27, and will margins recover to guided levels? Those numbers will separate hype from reality.
Sources (2): livemint.com, livemint.com (2)
This story was synthesised by AI from the 2 sources linked above.
Updated: this story now draws on 2 sources.