Now Reading: ITAT allows Rs 14.7L Section 54F deduction for Nagpur woman
-
01
ITAT allows Rs 14.7L Section 54F deduction for Nagpur woman

The Story in Brief
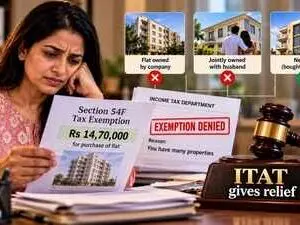
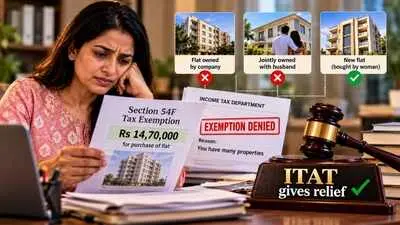
The Income Tax Appellate Tribunal (ITAT) has allowed a Nagpur woman's Rs 14.70 lakh deduction under Section 54F of the Income Tax Act for assessment year 2015-16, reversing the Commissioner of Income Tax (Appeals)'s order of 20 August 2025. The tax department had denied the exemption, arguing she owned more than one residential property.
The ITAT examined three properties the department cited. It held that one property belonged to a company where she was a director and could not be treated as her personal asset, and another was jointly owned with her husband, though she had not contributed to its purchase. The third property was the new house she acquired, which qualified for the exemption.
The tribunal concluded she owned only one residential house besides the new asset and thus met the conditions for the deduction. Tax experts note that fractional or joint ownership has often been distinguished from exclusive ownership in such cases by appellate authorities.
Indian Opinion Analysis
Times of India reports the tribunal's reasoning in detail, including the specific finding that company property cannot be treated as personal property merely because of directorship. Business Today's story on 21 October focuses on PAN misuse and a separate Delhi High Court case, not this ITAT ruling. The coverage of the Section 54F case is uniform straight reporting from Times of India, with no discernible slant. The key takeaway is the tribunal's distinction between ownership types, which offers a clear precedent for taxpayers facing similar denial of exemption.
Coverage: 2 sources, 2 neutral
Sources (2): timesofindia.indiatimes.com (neutral report), businesstoday.in (neutral report)
This brief was synthesised by AI from the 2 sources linked above, so one read covers every framing they carry. Methodology and corrections.