Now Reading: LIC profit rises 20% in Q2, flags ULIP volatility and persistency dip
-
01
LIC profit rises 20% in Q2, flags ULIP volatility and persistency dip
LIC profit rises 20% in Q2, flags ULIP volatility and persistency dip

The Story in Brief
Life Insurance Corporation of India reported a 20 per cent year-on-year rise in standalone net profit to Rs 12,076 crore for the quarter ended September 2026, driven by robust premium income growth. Net premium income rose 16.2 per cent to Rs 1,47,018 crore, while renewal premium grew to Rs 68,375 crore from Rs 64,996 crore a year earlier. However, first-year premium dipped slightly to Rs 10,432 crore from Rs 10,836 crore.
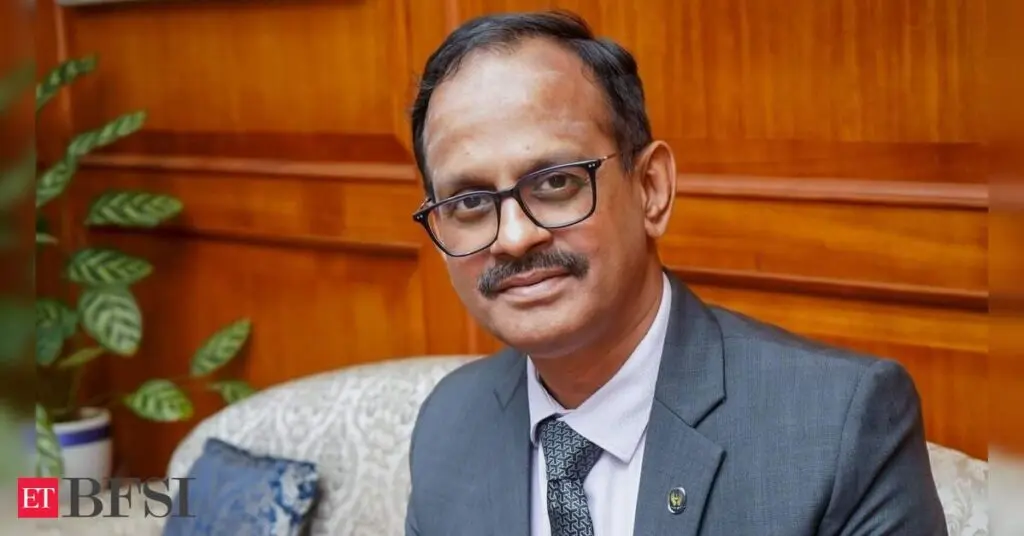
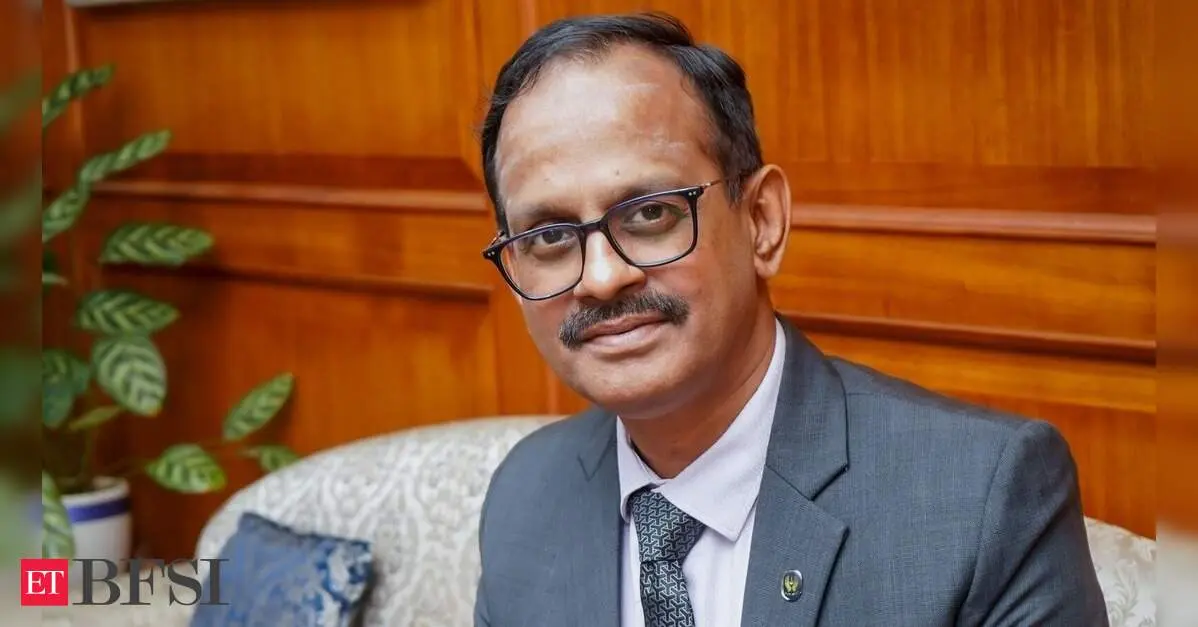
Managing Director and CEO R. Doraiswamy said on Thursday, 5 November, that ULIP sales and customer confidence are affected by volatile markets. LIC's 61st-month persistency on a premium basis fell to 61.03 per cent in the first half from 63.81 per cent a year earlier, with Doraiswamy attributing the decline to small-ticket policies. He said the insurer is nudging sales towards higher premium thresholds and increasing minimum ticket sizes.
On IRDAI's proposed commission and expense caps, Doraiswamy said LIC has sought global alignment and a glide path for compliance. He noted that some product lines would be impacted. The government and LIC have proposed selling a 60.72 per cent stake in IDBI Bank to Fairfax Financial Holdings for about Rs 52,878 crore. Doraiswamy said Q3 (October to December 2026) would be a deciding quarter for traction from new bank tie-ups including RBL Bank and Yes Bank.
Update, 6 November 2026: The New Indian Express and The Hans India now also report the story. Both confirm LIC's 20 per cent Q2 profit rise to Rs 12,076 crore and net premium income of Rs 1,47,018 crore. The New Indian Express adds that LIC sold 72,60,573 new individual policies in the quarter, up 2.25 per cent from a year earlier, and quotes Doraiswamy saying LIC is optimistic about the proposed commission regulation changes.
Indian Opinion Analysis
All four outlets report LIC's Q2 profit, persistency decline and IRDAI feedback in a straight, neutral-report style. The New Indian Express and The Hans India lead with the 20 per cent profit rise and premium growth, while Economic Times and Mint foreground the persistency drop and commission cap concerns. No outlet contradicts another on figures, they differ only in emphasis. The uniform coverage reflects the data-heavy nature of an earnings call with little political or ideological framing. The key item to watch is whether LIC's Q3 traction from new bank partners materialises as Doraiswamy projected on 5 November.
Coverage: 4 sources, 4 neutral
Sources (4): economictimes.indiatimes.com (neutral report), livemint.com (neutral report), thehansindia.com (neutral report), newindianexpress.com (neutral report)
This brief was synthesised by AI from the 4 sources linked above, so one read covers every framing they carry. Methodology and corrections.