Now Reading: UBS upgrades MCX to Buy, sets Rs 3,800 target on valuations
-
01
UBS upgrades MCX to Buy, sets Rs 3,800 target on valuations

The Story in Brief
The Story in Brief
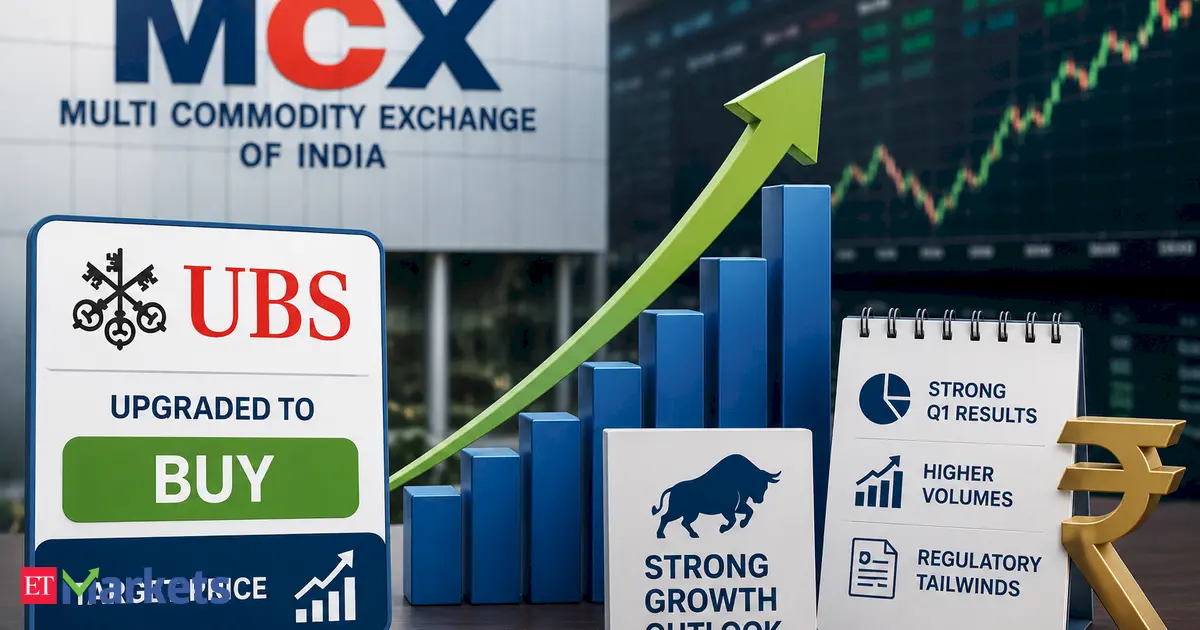
UBS has upgraded Multi Commodity Exchange of India (MCX) to Buy from Neutral and raised its 12-month price target to Rs 3,800 from Rs 3,600. The global brokerage cited attractive valuations after a 15% correction from May's peak, resilient trading volumes, and potential regulatory catalysts including Sebi's proposal for Foreign Portfolio Investment in commodity derivatives. UBS raised FY27-FY29 EPS estimates by 4%-9% and sees upside of over 28% from the previous close of Rs 2,962.
MCX shares traded at Rs 2,980 on Thursday, up 0.61%. The stock has risen nearly 35% in 2026, 78% in one year, and over 840% in three years. MCX's Q1 FY27 revenue surged 88% year-on-year to Rs 7 billion, supported by a 47% jump in futures average daily turnover. UBS expects EBITDA margins to expand to 77% by FY28 on operating leverage.
The Indian Opinion
Optimism about MCX often ignores regulatory uncertainty. The Sebi FPI proposal is just a consultation paper, not a done deal. Bulls cite 40x forward PE as cheap history, but that assumes smooth rule changes and sustained geopolitical volatility. The real test will come when the market prices in a failed or delayed FPI approval. Watchers should track Sebi's final circular, not broker upgrades, for the stock's true direction.
Source: economictimes.indiatimes.com
This story was synthesised by AI from the source linked above. Methodology and corrections.

Ashin Xavier: interesting
IO Repro: Repro test v4 after fix 2 Oct. Safe to trash.
IO Repro: Repro test v3 after fix 2 Oct. Safe to trash.
IO Repro: Repro test after fix 2 Oct. Safe to trash.