Now Reading: 9 reinvestment options to claim capital gains tax exemption
-
01
9 reinvestment options to claim capital gains tax exemption


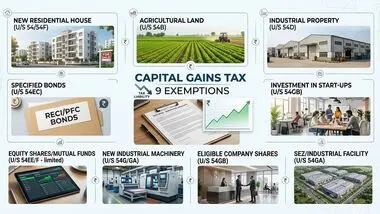
The Income-tax Act offers nine exemptions under Sections 54 to 54GB for capital gains tax if the gains or sale proceeds are reinvested in specified assets within prescribed timelines. The rules vary…
The Income-tax Act offers nine exemptions under Sections 54 to 54GB for capital gains tax if the gains or sale proceeds are reinvested in specified assets within prescribed timelines. The rules vary depending on the asset sold and the reinvestment vehicle. Section 54 allows exemption on selling a residential house and buying another, capped at Rs 10 crore or actual capital gains. Section 54F covers sale of shares or mutual funds to buy a house, with a Rs 10 crore ceiling, and does not apply if the taxpayer already owns more than one residential house.
Section 54B exempts gains from selling agricultural land if another agricultural land is bought within two years. Section 54EC permits investment in specified bonds like NHAI or REC within six months, with a Rs 50 lakh cap. Section 54GB allows reinvestment of residential property sale proceeds into equity shares of an eligible company or start-up. Each section has specific conditions on holding periods and eligible assets. The exemptions require strict adherence to timelines and investment limits.
Indian Opinion Analysis
These exemptions are designed to channel capital into housing, infrastructure, and start-ups rather than taxing gains immediately. The Rs 10 crore cap under Sections 54 and 54F was introduced in 2023, narrowing the benefit for high-value transactions. Section 54F's bar on owning more than one house before the reinvestment is a common pitfall for investors with multiple properties. For Section 54EC, the six-month window and Rs 50 lakh limit mean large gains may still attract tax on the surplus. Taxpayers should match the section to the asset class and timeline, as missing a deadline forfeits the exemption entirely. The next budget may revise these caps or conditions.
Source: livemint.com
This brief was synthesised by AI from the source linked above.