Now Reading: Afcons profits slump as payment delays hit execution
-
01
Afcons profits slump as payment delays hit execution


The Story in Brief
The Story in Brief
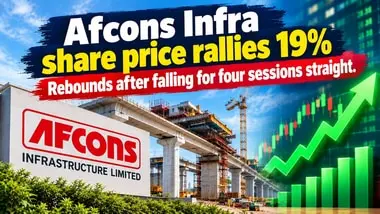
Afcons Infrastructure’s net profit fell to Rs 30 crore in Q1FY27 from Rs 137 crore a year ago, while total income dropped to Rs 2,727 crore from Rs 3,419 crore. The contractor’s EBITDA margin contracted to 9.6% from 13%. Livemint reports that payment delays and labour shortages are squeezing margins and delaying revenue conversion, overshadowing a record Rs 43,300-crore order book.
The stock has fallen 30% this year and 41% since its November 2024 listing. Analysts note that around 31% of the order book is slow-moving or at an early stage. However, the company won Rs 15,700 crore in new orders in Q1, including the Vadhavan Breakwater project and a Uganda road contract, providing execution visibility for three to four years.
The Indian Opinion
Afcons’ story is a classic case of a record order book not guaranteeing profits, a lesson Indian infrastructure investors keep learning. The narrative that a stock is a Buy because it has a fat order pipeline ignores that Afcons has 100% promoter pledge, rising debt, and delayed payments. The real test: can the company convert its Rs 43,300-crore backlog into cash flows over the next two quarters? Watch the receivable conversion, not just the order inflow headlines.
Source: livemint.com
This story was synthesised by AI from the source linked above. Methodology and corrections.


Ashin Xavier: interesting
IO Repro: Repro test v4 after fix 2 Oct. Safe to trash.
IO Repro: Repro test v3 after fix 2 Oct. Safe to trash.
IO Repro: Repro test after fix 2 Oct. Safe to trash.