Now Reading: Apollo Hospitals Q1 beats estimates, expansion plans on track
-
01
Apollo Hospitals Q1 beats estimates, expansion plans on track



Apollo Hospitals Enterprise’s June quarter earnings beat Street expectations, Livemint reports. Consolidated Ebitda margin expanded to 15.5% from 14.6% a year earlier, driven by higher patient volumes, increased average revenue per in-patient,…
The Story in Brief
Apollo Hospitals Enterprise’s June quarter earnings beat Street expectations, Livemint reports. Consolidated Ebitda margin expanded to 15.5% from 14.6% a year earlier, driven by higher patient volumes, increased average revenue per in-patient, and a smaller loss from the digital platform Apollo HealthCo. The healthcare services business, contributing 51% of revenue, grew 22% year-on-year to Rs 3,567 crore, with occupancy rising to 70% from 65%.
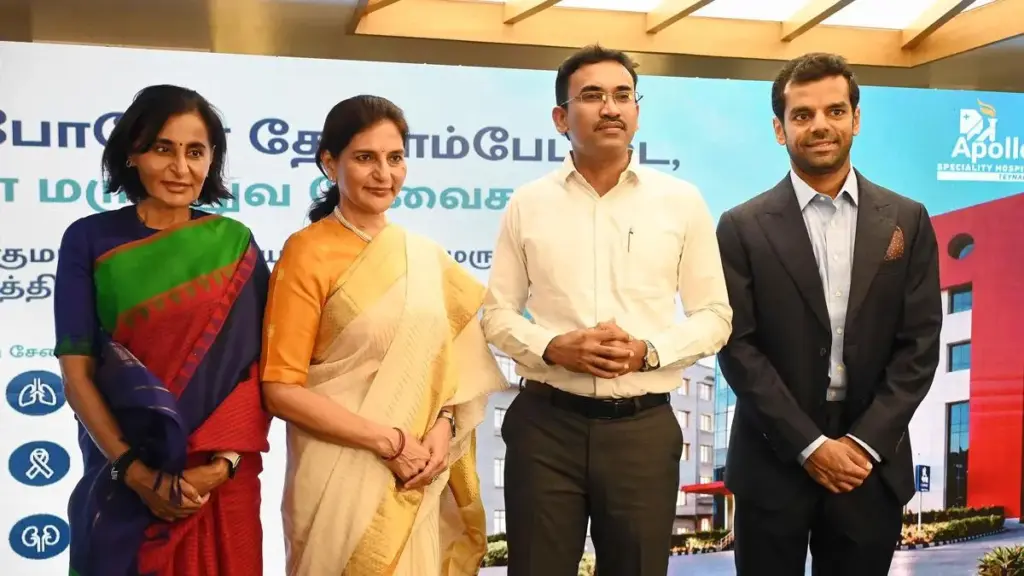
Apollo has commissioned five new hospitals with about 1,000 beds. Of these, 380 beds are already operational, and the remaining 620 will be ready over 12, 18 months. The expansion costs about Rs 11,150 crore, of which Rs 7,500 crore is yet to be spent. Brokerages remain divided: Citi maintained a 'buy' rating with a target price of Rs 10,770, while Motilal Oswal set a target of Rs 10,160. Nuvama Research said the digital business 24/7 is approaching breakeven.
The Indian Opinion
The hype around Apollo's Q1 beat masks a real near-term drag. New hospitals, especially the big Gurgaon facility, will dilute margins before they ramp up. Management itself guides for a Rs 150 crore loss from new hospitals in FY27. Investors should watch for one number: the month when Apollo 24/7 reports cash breakeven, now pushed to Q2FY27. Without that, HealthCo's demerger story loses some shine.
Sources (3): ndtvprofit.com, livemint.com, livemint.com (2)
This story was synthesised by AI from the 3 sources linked above.
Updated: this story now draws on 3 sources.