Now Reading: HAL Q1 profit jumps 15%, revenue up 14.4% year-on-year
-
01
HAL Q1 profit jumps 15%, revenue up 14.4% year-on-year



State-owned Hindustan Aeronautics (HAL) reported a 14.9% year-on-year jump in consolidated profit to Rs 1,589.68 crore for the June quarter, with revenue rising 14.4% to Rs 5,515.17 crore. EBITDA grew 19% to…
The Story in Brief
State-owned Hindustan Aeronautics (HAL) reported a 14.9% year-on-year jump in consolidated profit to Rs 1,589.68 crore for the June quarter, with revenue rising 14.4% to Rs 5,515.17 crore. EBITDA grew 19% to Rs 1,538 crore and the margin improved to 27.9%. On a standalone basis, net profit rose 14.8% to Rs 1,580.61 crore.
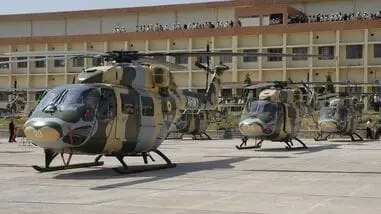
Brokerages have raised target prices after strong margins. Motilal Oswal, JPMorgan, Nomura and Kotak all cite healthy Q1, but flag the delivery of Tejas Mk1A aircraft as a key overhang. HAL has so far received seven GE F404 engines and targets first Tejas Mk1A delivery by August-September 2026.
The Indian Opinion
Brokerages are raising price targets but also flagging Tejas Mk1A delivery as a key risk. The narrative of an overhyped defence PSU ignores HAL’s 19% EBITDA margin improvement and a 13% year-to-date stock gain. The real test is not quarterly profit but execution: can HAL deliver the first Tejas Mk1A by August-September 2026 as targeted? That single milestone will either vindicate or puncture current valuations.
Sources (3): livemint.com, ndtvprofit.com, ndtvprofit.com (2)
This story was synthesised by AI from the 3 sources linked above.
Updated: this story now draws on 3 sources.