Now Reading: IRCTC Q1 profit flat at Rs 330 crore, revenue up 18%
-
01
IRCTC Q1 profit flat at Rs 330 crore, revenue up 18%



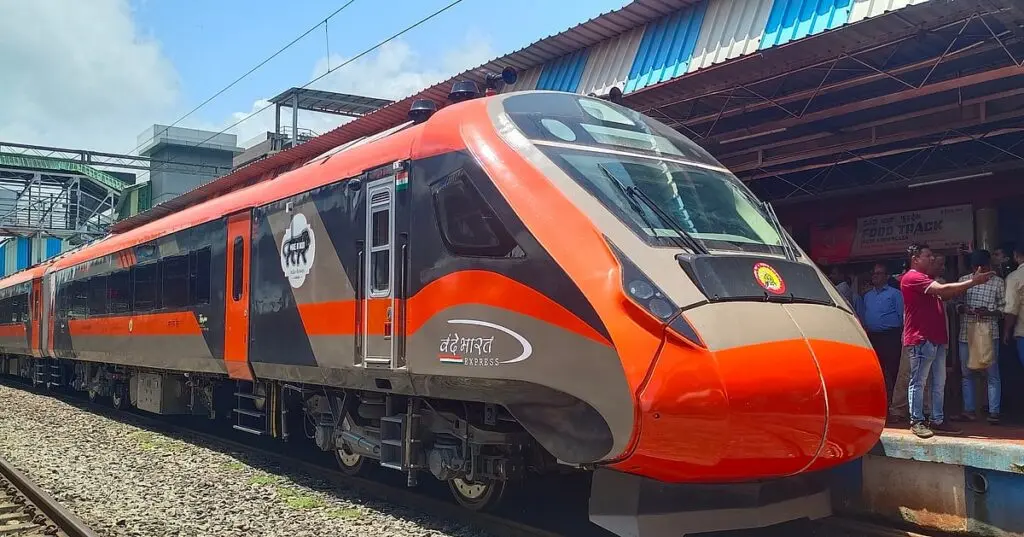
IRCTC reported a consolidated net profit of Rs 330.16 crore for the June quarter, nearly flat from Rs 330.71 crore a year ago. Revenue rose 18.1% year-on-year to Rs 1,369.53 crore, driven…
The Story in Brief
IRCTC reported a consolidated net profit of Rs 330.16 crore for the June quarter, nearly flat from Rs 330.71 crore a year ago. Revenue rose 18.1% year-on-year to Rs 1,369.53 crore, driven by a 33.9% jump in catering revenue, though tourism revenue fell sharply from the March quarter. EBITDA margin slipped to 28.2% from 34% last year, hit by one-time employee costs and input inflation, Livemint and The Hindu Business Line report.
The stock closed at Rs 497.50, down 1.38%, and has lost over 60% from its all-time high of Rs 1,318 in May 2024. PL Capital has retained a buy rating on IRCTC with a target price of Rs 706, citing decent growth prospects, a debt-free balance sheet, and healthy return ratios despite the margin dip. The brokerage expects catering and Rail Neer expansion to drive an 11% sales CAGR over FY26-FY28E.
The Indian Opinion
Some analysts read IRCTC's flat profit as a sign of fatigue, but the 18% revenue jump and sturdy catering growth tell a more nuanced story. The stock's 60% slide from its peak may reflect market impatience, yet the company's debt-free balance sheet and planned Rail Neer capacity expansion offer concrete reasons for measured optimism. The real test: can IRCTC lift its EBITDA margin back above 30% while scaling up lower-margin catering, or will costs keep eating into gains?
Sources (2): livemint.com, thehindubusinessline.com
This story was synthesised by AI from the 2 sources linked above.
Updated: this story now draws on 2 sources.