Now Reading: Know privacy risks before sharing fitness data with insurer
-
01
Know privacy risks before sharing fitness data with insurer


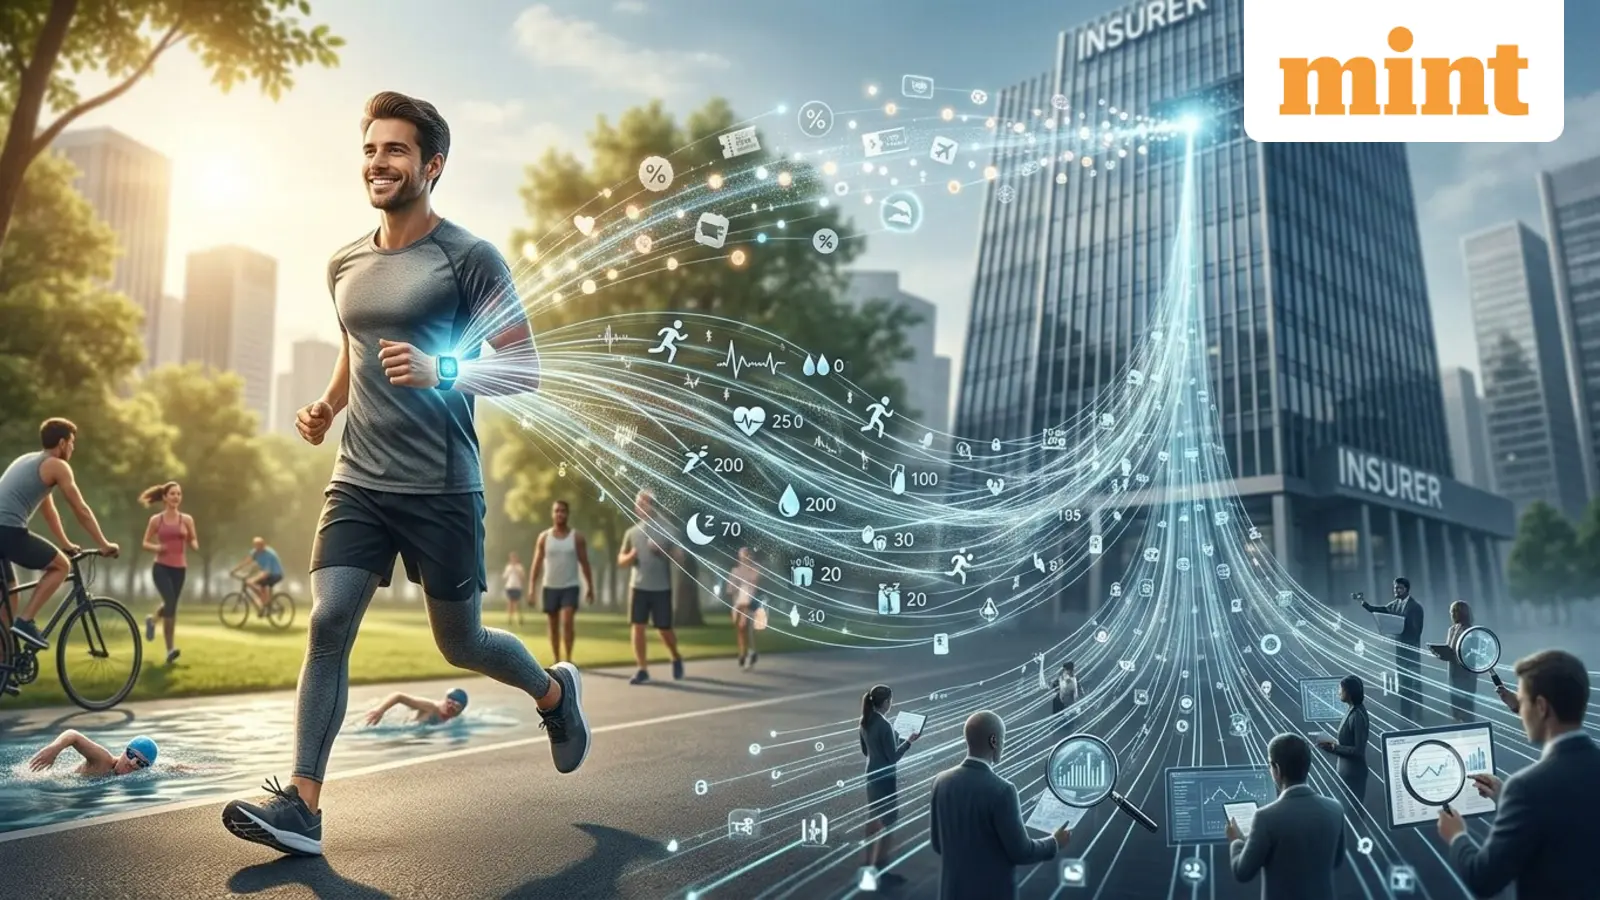
Health insurers in India are offering wellness programmes that reward policyholders for activities like walking, swimming or cycling, but consumers may be overlooking the privacy trade-off. Participants may have to share personal…
Health insurers in India are offering wellness programmes that reward policyholders for activities like walking, swimming or cycling, but consumers may be overlooking the privacy trade-off. Participants may have to share personal health and fitness data, including step counts, exercise patterns, sleep cycles, and diet logs, through apps, wearables or connected devices.
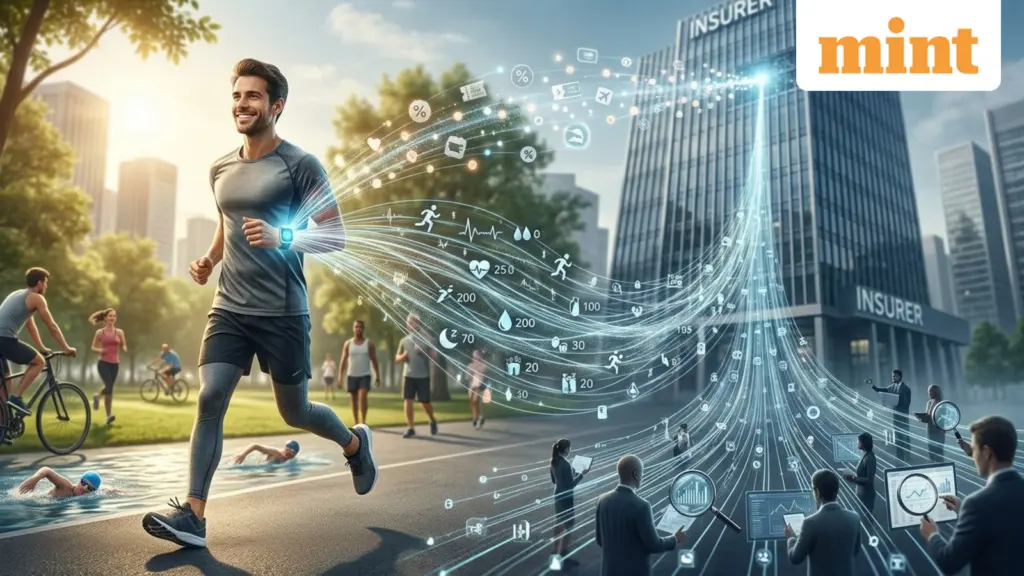
The exact information collected varies by insurer and programme, according to executives at Universal Sompo General Insurance and IFFCO-TOKIO General Insurance. They said customers should carefully review consent terms and privacy conditions before signing up, and check who can access the data, how long it will be retained, and whether it can be used for purposes beyond the wellness benefit.
Wellness rewards are typically structured as points redeemable for discounts on renewal premiums or preventive healthcare services. The executives said such programmes are designed to reward healthy behaviour and do not affect claim settlement, but consumers should read the policy terms to understand conditions attached to earning and redeeming rewards.
Indian Opinion Analysis
Wellness programmes are a relatively new feature in India's health insurance market, which is regulated by the Insurance Regulatory and Development Authority of India (IRDAI). The regulator's 2024 guidelines on insurance web aggregators and digital platforms require explicit consent for data sharing, but they do not specifically address wellness programme data. Consumers should note that once health data is shared with an insurer, it becomes part of the policyholder's digital footprint and may be accessible to technology partners or reinsurers, though the IRDAI restricts its use for underwriting or claims. The key risk is not that poor fitness data will raise premiums today, but that future policy terms or regulatory changes could allow such data to be used for risk profiling.
Source: livemint.com
This brief was synthesised by AI from the source linked above.