Now Reading: Property bought below stamp duty value may avoid tax within 10% tolerance
-
01
Property bought below stamp duty value may avoid tax within 10% tolerance

Property bought below stamp duty value may avoid tax within 10% tolerance

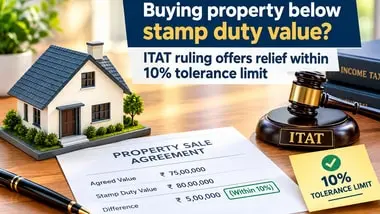
A Pune bench of the Income Tax Appellate Tribunal (ITAT) ruled that the difference between a property's purchase price and its stamp duty valuation is not automatically taxable if it falls within…
A Pune bench of the Income Tax Appellate Tribunal (ITAT) ruled that the difference between a property's purchase price and its stamp duty valuation is not automatically taxable if it falls within the 10% tolerance limit. In the case of Aslam Sadule Khan, a land parcel bought for Rs 3.91 crore was valued at Rs 6 crore by stamp duty authorities. The Departmental Valuation Officer assessed it at Rs 4.031 crore, reducing the gap to Rs 12.10 lakh, or about 3% of the purchase price, well within the limit. The tribunal directed the Assessing Officer to revise the assessment.
Separately, the Delhi ITAT on September 16, 2026, quashed a Rs 70,700 penalty under Section 270A against a Ghaziabad buyer, Rai, who purchased property for Rs 48 lakh against a stamp duty value of Rs 58.7 lakh. The tribunal held that the tax department failed to prove mala fide intention, and Rai's case fell within the statutory exception for bona fide explanations under Section 270A(6)(a). Rai had disclosed the differential income and paid tax after receiving a notice.
Both rulings underscore that the tax treatment depends on the facts of each case, including the actual valuation and the buyer's explanation. Buyers should retain all transaction documents and consult a tax professional.
Indian Opinion Analysis
Both sources report tax tribunal rulings favourably for buyers but frame them differently. Livemint leads with the 10% tolerance limit and the DVO's role, presenting a rule-based framework that taxpayers can rely on. Economic Times leads with the penalty being quashed due to lack of mala fide intent, framing the win as a matter of the department's failure of proof. The difference matters: Livemint's framing implies a safe harbour if the gap is under 10%, while Economic Times suggests even a larger gap may be protected if the buyer offers a bona fide explanation. Neither ruling creates a blanket exemption, both depend on taxpayers meeting specific statutory conditions. The next test will be how consistently lower tax authorities apply these exceptions in similar cases.
The rulings show that the 10% tolerance under Section 50C and the bona fide explanation exception under Section 270A(6)(a) are the key legal shields for buyers.
Coverage: 2 sources, 2 neutral
Sources (2): livemint.com (neutral report), economictimes.indiatimes.com (neutral report)
This brief was synthesised by AI from the 2 sources linked above, so one read covers every framing they carry.
Updated: this story now draws on 2 sources.