Now Reading: SEBI to address expiry-day settlement price concerns
-
01
SEBI to address expiry-day settlement price concerns


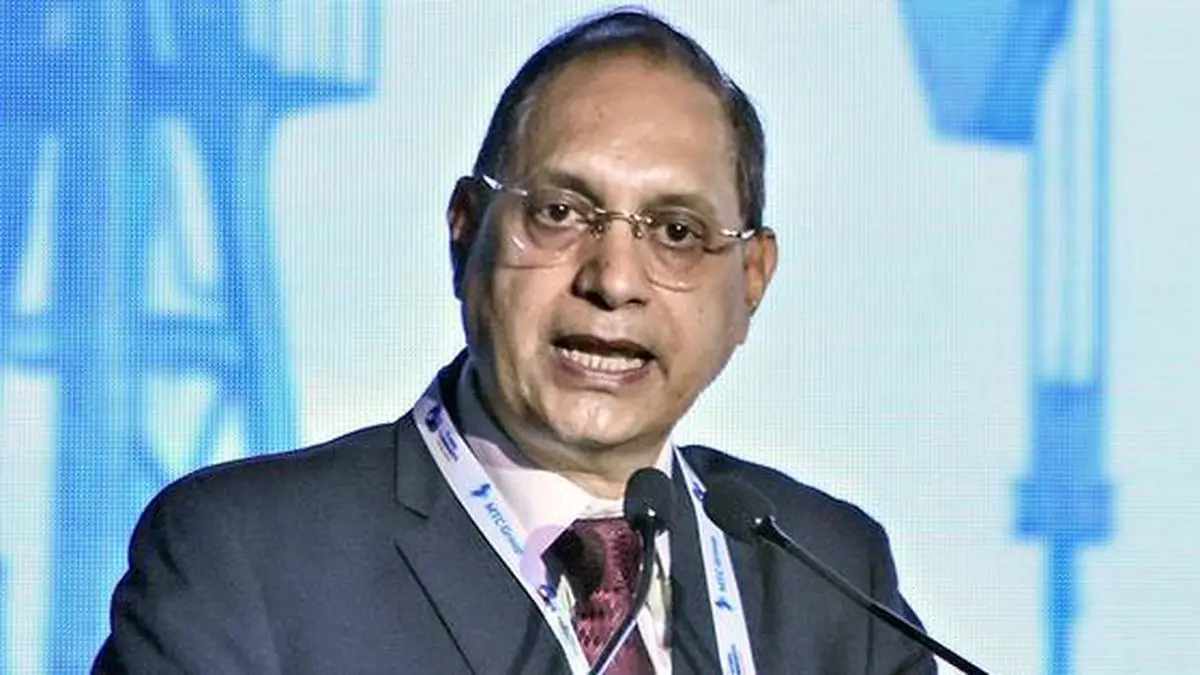
SEBI chairman Tuhin Kanta Pandey said the regulator intends to address concerns over the settlement price for derivatives on expiry days. A consultation paper issued earlier this month proposes two options: a…
SEBI chairman Tuhin Kanta Pandey said the regulator intends to address concerns over the settlement price for derivatives on expiry days. A consultation paper issued earlier this month proposes two options: a blended volume-weighted average price (VWAP) using the last 30 minutes of continuous trading and the 10-minute closing auction session, or retaining the existing CTS VWAP as an interim measure. The proposals also include delinking derivative settlement prices from the cash-market closing price.
Pandey spoke at the JP Morgan India Conference in New Delhi. Separately, at the SBI Banking and Economics Conclave, he said SEBI is open to reviewing margin requirements for longer-dated derivatives to encourage broader participation beyond short-term index options. A SEBI study for FY26 found 87.7% of individual traders lost money in equity derivatives, though aggregate losses fell to Rs 91,686 crore.
Indian Opinion Analysis
The coverage across the three sources is uniform straight reporting, with no discernible slant. All report Pandey's statements and the consultation paper details neutrally. The Livemint story adds context from SEBI's trader loss study and margin review discussion, providing broader regulatory background. The balanced reading is that SEBI is proceeding methodically with market reforms while addressing participant feedback and retail trader risks.
Coverage: 3 sources, 3 neutral
Sources (3): thehindubusinessline.com (neutral report), newindianexpress.com (neutral report), livemint.com (neutral report)
This brief was synthesised by AI from the 3 sources linked above, so one read covers every framing they carry.
Updated: this story now draws on 3 sources.