





Now Reading: Taxpayers can file ITR early despite audit deadline extension
-
01
Taxpayers can file ITR early despite audit deadline extension


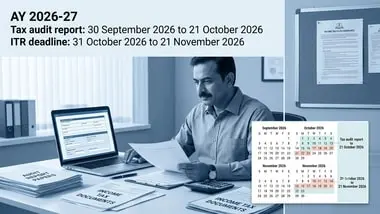
The tax audit deadline for assessment year 2026-27 has been extended from 30 September to 21 October 2026, but taxpayers who have completed their audit can file their income tax return immediately…
The tax audit deadline for assessment year 2026-27 has been extended from 30 September to 21 October 2026, but taxpayers who have completed their audit can file their income tax return immediately without waiting for the new deadline. The ITR due date has also moved in tandem to 21 November 2026 to preserve the statutory one-month gap between the audit report and the return.
Chartered accountant Isha Sekhri said there is no legal requirement to delay filing, as the extension is relief and not a mandate. Taxpayers should verify that the audit report shows "Approved" status with a valid UDIN on the ICAI portal, reconcile figures with audited financial statements, and match PAN and assessment year details exactly.
If a mistake in the audit report is found after filing, taxpayers can file a revised return by 31 December 2026 under Section 139(5). The correct sequence is to have the chartered accountant correct and re-file the audit report first, followed by a revised ITR referencing the corrected report.
Indian Opinion Analysis
The one-month gap between the audit report and ITR due dates is built into the tax code to give accountants time to reconcile final figures after the audit is lodged, so the extended 21 October date for the audit does not trigger an automatic extension for all taxpayers, only those who need it. Taxpayers whose audits were finished by the original 30 September deadline have historically filed early without penalty, and the Income Tax Department has not flagged early filing as a violation. The key risk for anyone filing early is that Form 26AS, AIS, and TIS data can be updated by deductors after the return is filed, and a mismatch on the department's portal after 21 November could still generate an automated notice under Section 143(1).
Source: livemint.com
This brief was synthesised by AI from the source linked above. Methodology and corrections.