Now Reading: Tax audit deadline stays Sept 30, no extension yet
-
01
Tax audit deadline stays Sept 30, no extension yet


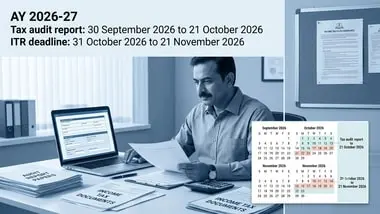
The September 30 deadline for filing tax audit reports remains in force with no extension granted, despite demands from tax professionals and industry bodies. Late filers face a penalty under Section 271B…
The September 30 deadline for filing tax audit reports remains in force with no extension granted, despite demands from tax professionals and industry bodies. Late filers face a penalty under Section 271B of 0.5% of total turnover or gross receipts, though relief is available under Section 273B if reasonable cause is shown. A delayed audit that pushes the October 31 ITR deadline also attracts interest under Section 234A and late filing fees.
Tax professionals argue the packed September compliance calendar and technical difficulties with tax utilities make timely completion difficult. Hashtag #ExtendTaxAuditDueDate has gained traction on social media. Meanwhile, experts advise auditors to reconcile books with GST returns, AIS, TIS and Form 26AS before final submission. Tax audit applies to businesses with turnover above Rs 1 crore and professionals with gross receipts above Rs 50 lakh.
Indian Opinion Analysis
Both sources treat the September 30 tax audit deadline as a matter-of-fact compliance date. Livemint leads with the penalty under Section 271B and professionals' extension demands, giving space to the hashtag #ExtendTaxAuditDueDate. Times Now leads with reconciliation checklists and Deloitte's guidance, never mentioning the extension demand. Livemint reports a strained system, Times Now reports a manageable process, implying taxpayers can comply with proper checks. A reader aware of both sees a department preparing to enforce the deadline while professionals flag genuine workload pressure. Whether the government grants relief before Wednesday remains the concrete outcome to watch.
Coverage: 2 sources, 2 neutral
Sources (2): livemint.com (neutral report), timesnownews.com (neutral report)
This brief was synthesised by AI from the 2 sources linked above, so one read covers every framing they carry.
Updated: this story now draws on 2 sources.