Now Reading: When to declare foreign ESOPs in ITR: Tax guide for employees
-
01
When to declare foreign ESOPs in ITR: Tax guide for employees


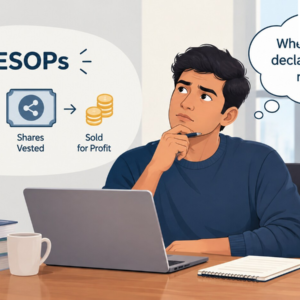
Indian employees of foreign companies who receive employee stock options (ESOPs) as part of their compensation need to understand the tax and disclosure timeline. The reporting obligation depends on the stage at which the employee holds or acquires the foreign shares.
ESOPs do not trigger a tax obligation merely upon grant. Taxation occurs in two stages: at exercise, when the difference between fair market value and exercise price is taxed as a perquisite under salary income, and at sale, when the sale price minus that fair market value is taxed as capital gains.
To avoid double taxation, India has Double Tax Avoidance Agreements with several countries, including the United States. Employees who have had foreign tax withheld may claim a foreign tax credit while filing their Indian ITR, subject to applicable rules.
Indian Opinion Analysis
This guide clarifies that for Indian employees of foreign firms, ESOP tax liability arises only at exercise and sale, not at grant. The key compliance step is reporting the perquisite value from exercise under salary income in the relevant financial year. Later, capital gains tax applies on sale, with holding periods of 12 months distinguishing long-term from short-term gains. The article leaves unresolved how employees should document foreign tax withheld and claim the credit under India's Double Tax Avoidance Agreements, a process that depends on the specific foreign employer and country involved.
Source: livemint.com
This brief was synthesised by AI from the source linked above. Methodology and corrections.