Now Reading: Credit card EMI vs personal loan: what costs less
-
01
Credit card EMI vs personal loan: what costs less


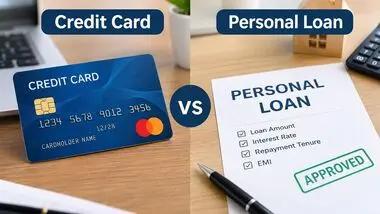
A lower monthly EMI does not always mean a cheaper loan. Livemint reports that before choosing between a credit card EMI and a personal loan, borrowers should calculate the total amount payable…
A lower monthly EMI does not always mean a cheaper loan. Livemint reports that before choosing between a credit card EMI and a personal loan, borrowers should calculate the total amount payable under both options, including interest, processing fees, GST, and any prepayment charges. For smaller purchases, a genuine no-cost credit card EMI may be useful, but borrowers should check if the offer involves giving up an instant cash discount.
For larger expenses, a personal loan may have a lower overall cost if the interest rate and charges are more favourable. Livemint also warns that zero-cost EMI schemes often embed the interest into the product's sale price, and that processing fees, convenience fees, and taxes can raise the effective cost. Borrowers should compare the EMI price with the outright purchase price and check for lock-in periods and early closure charges.
As a general rule, total EMIs across all loans should ideally stay within 40% of monthly take-home income. Borrowers should also ensure sufficient funds are in the linked account before an auto-debit, and if a payment fails, they should pay manually within 24-48 hours and request a waiver of charges from the lender.
Indian Opinion Analysis
Both livemint articles adopt a consumer-advice framing, warning that advertised EMIs and zero-cost offers can mask higher effective costs. The first piece focuses on comparing credit card EMI and personal loans for big-ticket purchases, while the second broadens the warning to consumer durable loans and includes legal consequences under the Payment and Settlement Systems Act. Neither article shows a government or political slant, the stance is neutral consumer guidance. A balanced reading is that while EMI options offer convenience, the true cost depends on processing fees, interest, and foregone discounts, and borrowers should calculate total outlay before deciding.
Coverage: 2 sources, 2 neutral
Sources (2): livemint.com (neutral report), livemint.com (2) (neutral report)
This brief was synthesised by AI from the 2 sources linked above, so one read covers every framing they carry.
Updated: this story now draws on 2 sources.