Now Reading: Closing unused credit card can raise utilisation ratio, hurt score
-
01
Closing unused credit card can raise utilisation ratio, hurt score

Closing unused credit card can raise utilisation ratio, hurt score

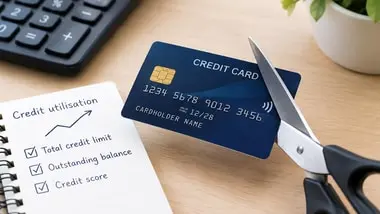
Closing an unused credit card reduces total available credit, which can push the credit utilisation ratio higher and potentially lower the credit score. For example, if total limits drop from Rs 5…
Closing an unused credit card reduces total available credit, which can push the credit utilisation ratio higher and potentially lower the credit score. For example, if total limits drop from Rs 5 lakh to Rs 3 lakh while outstanding balances stay at Rs 1 lakh, utilisation rises from 20% to 33.3%.
Experts recommend keeping the card active with small, infrequent transactions paid in full each month. If the annual fee is a concern, cardholders can negotiate a waiver or downgrade to a lifetime free variant. Closing a card may be justified if it carries a high fee, offers poor benefits, or risks overspending.
The credit utilisation ratio above 30% is a common threshold, though not a rigid cutoff. Borrowers should review other card limits, outstanding balances, and whether the card is among their oldest accounts before deciding. Card closure, unlike blocking or deactivation, terminates the account and must be processed within seven working days of settlement.
Indian Opinion Analysis
The credit utilisation ratio is one of several factors credit bureaus such as CIBIL and Experian use in scoring models. A spike above 30% on an individual card or across all cards can signal higher risk to lenders, potentially leading to higher interest rates or lower limits on new loans. For Indian borrowers, keeping an old card open also preserves the length of credit history, a scoring component that cannot be rebuilt quickly. The practical trade-off is between a small annual fee and the invisible cost of a lower score. Cardholders should check whether their issuer offers a lifetime free downgrade or a fee waiver, as many do, before opting for closure.
Source: livemint.com
This brief was synthesised by AI from the source linked above.