Now Reading: TDS on contractor payments: New rules under Income Tax Act 2025
-
01
TDS on contractor payments: New rules under Income Tax Act 2025


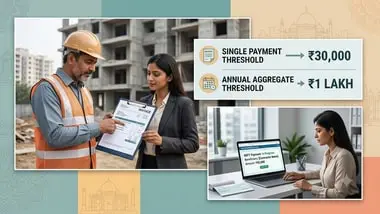
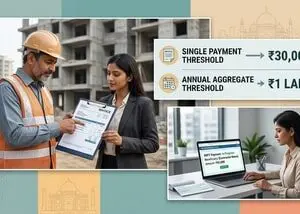
Payments made to contractors for construction, repair or renovation work from 1 April 2026 are subject to TDS under Section 393(1) of the Income-tax Act, 2025. For a company, firm or government body paying a resident contractor, TDS is 1% if the contractor is an individual or HUF, and 2% for other entities. TDS must be deducted when the payment is booked or made, whichever comes first.
An individual or HUF making such payments must deduct TDS at 2% if the total payment in a financial year exceeds Rs 50 lakh. No TDS applies to a single payment of Rs 30,000 or less for designated persons, but the requirement kicks in if aggregate payments to a contractor cross Rs 1 lakh in a year.
Indian Opinion Analysis
The rules create two different thresholds depending on who is paying: designated persons such as companies and government bodies face a Rs 1 lakh annual aggregate trigger, while individuals and HUFs have a higher Rs 50 lakh limit before TDS applies. The distinction means a householder building a home can pay up to Rs 50 lakh to a contractor without TDS, but a company paying the same contractor for an identical job must deduct TDS once annual payments exceed Rs 1 lakh. The source leaves open how a payer should treat mixed payments that cross both thresholds, or what documentation the contractor must provide to claim the TDS credit.
Source: livemint.com
This brief was synthesised by AI from the source linked above. Methodology and corrections.