Now Reading: 60% of borrowers’ EMIs near or exceed family income: survey
-
01
60% of borrowers’ EMIs near or exceed family income: survey


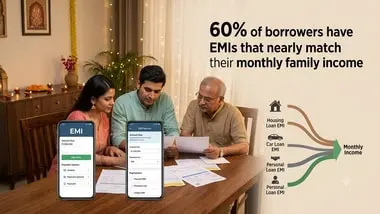
A survey by debt resolution platform Expert Panel has found that 60% of borrowers have EMIs that either exceed or nearly equal their total monthly family income. The survey also revealed that…
A survey by debt resolution platform Expert Panel has found that 60% of borrowers have EMIs that either exceed or nearly equal their total monthly family income. The survey also revealed that 40% of borrowers are managing existing EMIs by taking new loans or using credit cards, indicating a stretched household budget.
Medical emergencies were the most common reason for borrowing, cited by 26% of respondents. Another 22% borrowed for family expenses including weddings and education, while 18% cited business needs or job loss. The survey noted that 39% of borrowers who struggled to repay reported recovery calls or abusive language, and 35% faced some form of harassment.
The platform's director advised consumers to assess total borrowing cost and existing EMI commitments before taking a festive-season loan. Borrowers were urged to calculate all existing EMIs and check whether income can absorb an additional EMI if an unexpected expense arises.
Indian Opinion Analysis
The survey points to a debt trap where fresh borrowing is used to service older loans, a cycle the RBI has repeatedly flagged as a risk to household financial stability. The central bank's Financial Stability Report of June 2024 noted that household debt as a share of GDP had risen to an all-time high, and stressed that unsecured personal loans were growing at over 20% year-on-year. In response, the RBI tightened norms for personal loans and credit cards in late 2023, raising risk weights on such lending. The key figure to watch now is the share of borrowers who default within 90 days on these unsecured loans, which will determine whether further regulatory curbs are needed. The RBI's next Financial Stability Report, due in December, will show whether the tightening has cooled lending or if households remain overleveraged.
Source: livemint.com
This brief was synthesised by AI from the source linked above.