Now Reading: Repaid a loan but credit report still shows it active? Experts explain how to fix it
-
01
Repaid a loan but credit report still shows it active? Experts explain how to fix it

Repaid a loan but credit report still shows it active? Experts explain how to fix it

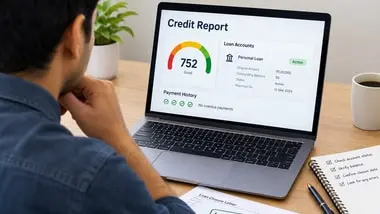
Repaying a loan does not automatically update your credit report. Lenders send data periodically to credit bureaus, so a closed loan may continue to appear as 'active' for a while. Borrowers should…
Repaying a loan does not automatically update your credit report. Lenders send data periodically to credit bureaus, so a closed loan may continue to appear as 'active' for a while. Borrowers should first check with the lender to confirm the account has been marked as closed and keep the closure letter, no-due certificate and final payment receipt handy. If the status persists, raise a dispute with the credit bureau by submitting supporting documents.
Under the RBI framework, compensation of Rs 100 per calendar day may be payable if a complaint regarding credit information rectification is not resolved within 30 calendar days of filing. Borrowers should check the account status, outstanding balance, closure date and payment history on their report. An accurate credit profile helps in future loan and credit card applications.
Indian Opinion Analysis
The RBI's compensation rule for delayed credit report updates, ₹100 per day of delay after 30 days for filing a complaint, exists because banks and credit bureaus update data in periodic batches, not in real time. An incorrect 'active' status on a closed loan can drop a borrower's credit score by 50, 100 points, which then affects interest rates on any new loan application. Borrowers should always demand a 'loan closure certificate' and a 'no-due certificate' at the time of final payment, and retain the settlement letter. The key step is to raise a written dispute with the credit bureau (CIBIL, Experian, Equifax or CRIF High Mark) through its online portal, attaching scanned copies of those documents. If the bank fails to update within 30 calendar days of the complaint, the compensation clock starts.
Source: livemint.com
This brief was synthesised by AI from the source linked above.